My Husband Wouldn’t Name Me as His Beneficiary — So I Made a Tough Choice
Money can be a sensitive topic in any marriage, especially when children from past relationships are involved. One woman shared how a disagreement over life insurance left her questioning whether she and her husband were truly looking out for each other.
The couple had been married for just over a year. The woman had two grown daughters from an earlier relationship. Having lost both her parents while she was in her 30s, she knew how hard life could become after losing someone close.
That experience taught her the value of planning ahead. She made sure her life insurance and other accounts would provide support for both her daughters and her husband if anything happened to her.
But when she asked her husband to make similar plans, his answer caught her off guard.
He refused to name her as a beneficiary on his life insurance policy. Instead, he wanted his mother to receive everything, even though they hadn’t been close for years.
The woman struggled to understand his choice. She had taken steps to protect him, yet he wasn’t willing to offer her the same support.
After thinking it over, she made a decision of her own. She removed her husband from her policies and arranged for her daughters to receive the money instead.
To her, it seemed fair. If her husband wanted to decide who would benefit from his policy, she felt she should have the same freedom.
But her husband didn’t see it that way.
He was upset when he learned about the change. He felt she was leaving him without financial support if something happened to her.
The disagreement soon raised a bigger question about their marriage. Why did he expect to benefit from her plans while refusing to include her in his own?
The story got people talking about fairness, trust, and money in blended families. It also showed how important it is for couples to discuss their future plans before a crisis forces them to make difficult choices.
Add a stronger opening hookClarify the insurance disagreement
At first, this might sound like a small argument about life insurance. But for this couple, it brought up much bigger questions about money, trust, and looking after each other.
Life insurance isn’t just another bill to pay. For many families, it’s a safety net that can help loved ones manage expenses after someone dies.
The wife understood this better than most.
Advertisement – Continue Reading Below
She lost both her parents while she was in her 30s. Along with the grief, she had to deal with their money, property matters, and funeral costs. Going through all of that taught her how important it was to prepare for the unexpected.
She didn’t want her own children to face the same struggles.
That’s why she kept life insurance policies that would provide money for her two grown daughters if anything happened to her.
When she remarried, she also wanted to make sure her new husband would be taken care of.
She bought a separate $100,000 life insurance policy with him as the beneficiary. Since he earned less than she did, she believed the money could help him cover bills and other expenses if she passed away.
To her, it was a way of showing love and making sure her family would have some financial support during a hard time.
But things became tense when she asked her husband about his own life insurance.
He had a policy through his job, and she wanted him to name her as a beneficiary.
His answer surprised her.
He refused.
Instead, he wanted his mother to remain the only person who would receive the money.
According to the wife, her mother-in-law was doing well financially. She also said her husband and his mother hadn’t shared a close relationship for years.
That made his decision even harder for her to understand.
She wasn’t asking him to stop caring about his mother. She simply wanted to know that he was also thinking about her future.
For many married couples, life insurance is one way to protect each other. If one partner dies, the money can help the other manage bills, housing costs, and other needs.
Of course, every family has different reasons for choosing beneficiaries. Some people want to support parents, children, or other loved ones.
But when spouses have very different plans, those choices can lead to hurt feelings.
That’s what happened here.
The wife felt she was doing everything she could to protect her husband, while he wasn’t willing to offer her the same support.
After thinking about it, she decided to change her own plans.
She removed her husband from the policy she had bought for him and made sure her daughters would receive the benefits instead.
Some readers felt this was a fair response. If her husband had the right to choose his mother, they believed she had the same right to choose her children.
Others might see the decision as too harsh.
After all, marriage isn’t always about making sure both people do the exact same thing. Couples may have different financial needs and family duties.
Still, the wife didn’t see her choice as punishment.
She saw it as a way to protect her money and make sure her daughters would be supported.
The fact that she had children from an earlier marriage also made the situation more complex.
Blended families often have to think carefully about who will receive money, property, or other assets after someone dies.
A parent may want to provide for their children while also helping a new spouse.
There isn’t one plan that works for every family. What matters is making those choices clear and making sure everyone understands them.
The wife had already taken steps to protect both her daughters and her husband. But after learning about his decision, she began questioning whether their plans were fair.
She also wondered why he expected financial help from her when he wasn’t willing to provide the same kind of protection.
That question became the heart of their disagreement.
Some people might argue that the couple should have kept talking until they found a middle ground.
For example, they could have discussed splitting the insurance money between different family members. They also could have looked at their income, debts, savings, and future needs before making a choice.
But according to the wife, this wasn’t a new argument.
She said they had been discussing the issue for more than a year without reaching an agreement.
Eventually, she felt she couldn’t keep waiting for him to change his mind.
Her decision also brought attention to a common problem in marriages: one person feeling they are giving more than they receive.
That feeling isn’t always about money.
Sometimes, it’s about wanting to know your partner cares about your needs as much as their own.
The wife wanted to feel secure. She wanted to believe that if something happened to her husband, she wouldn’t be left facing every financial problem alone.
When he refused to include her in his policy, she felt that sense of security was missing.
At the same time, her husband was upset when he learned she had removed him from her own coverage.
He felt she was leaving him without financial support if she died.
From her point of view, his reaction seemed unfair. He wanted her to keep protecting him, even though he had chosen not to do the same for her.
This difference in expectations made the argument about much more than an insurance policy.
It became a question of trust and how they viewed their duties to each other.
Money talks can be uncomfortable, especially when they involve death, family members, and future plans.
But avoiding those talks can create bigger problems later.
Couples can benefit from sitting down together and reviewing their insurance, savings, debts, and other financial plans.
They should also talk about who depends on them for support and what might happen if one partner is no longer there.
For blended families, these talks can be even more important.
Children from past relationships, aging parents, and new spouses may all have different needs. Making clear plans can help prevent confusion and family disputes later.
It’s also worth checking beneficiary details from time to time. Marriage, divorce, a new child, or a change in family needs can all be reasons to review those choices.
For this woman, updating her policies was a way to take control of her own future.
She had learned from losing her parents that life can change without warning. She didn’t want to leave important money decisions until it was too late.
But there was also an emotional cost.
She still wanted to care for her husband. She simply wanted to feel that he cared about her future too.
That’s what made the situation so painful.
Both partners felt hurt, but for different reasons. He was upset about losing the financial protection she had arranged for him. She was upset because he had refused to offer her similar support.
The story shows how quickly money disagreements can affect trust in a marriage.
It also reminds couples that financial planning isn’t just about choosing names on a form. It’s about understanding each other’s needs, hopes, and concerns.
Protecting your family doesn’t mean expecting something bad to happen. It means making thoughtful choices now so loved ones have fewer worries later.
For this wife, that meant putting her daughters first after realizing she and her husband didn’t share the same views about financial support.
Whether others agree with her decision or not, her story raises an important question: How can two people build a secure future together when they have very different ideas about protecting each other?
The Comments Are In
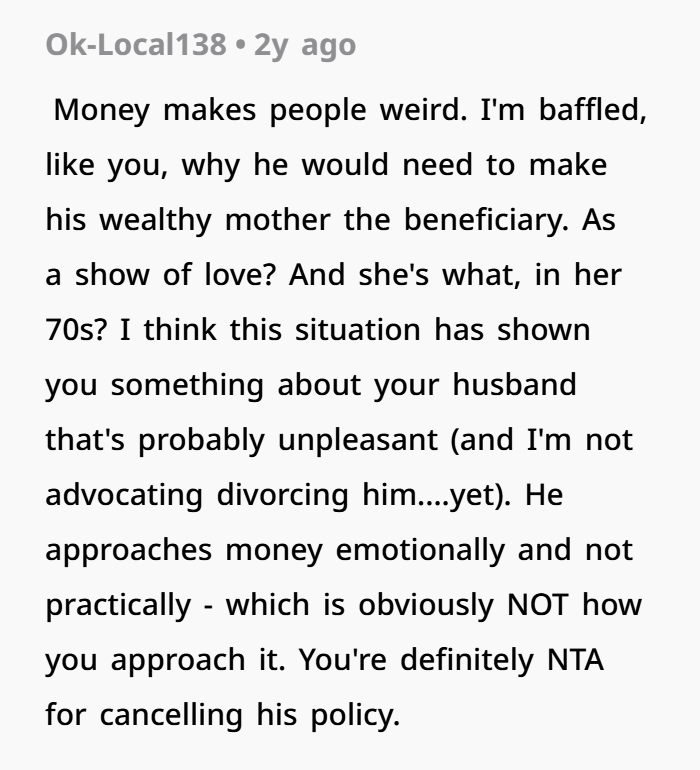
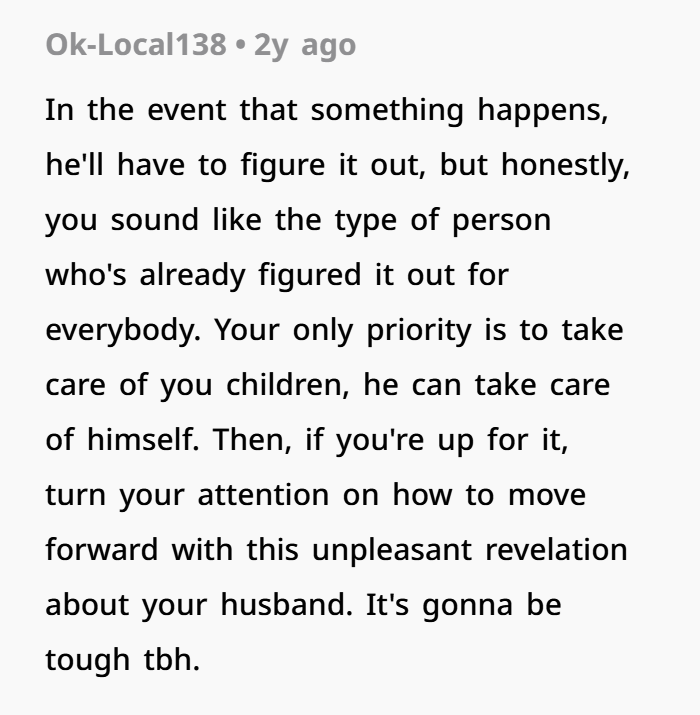
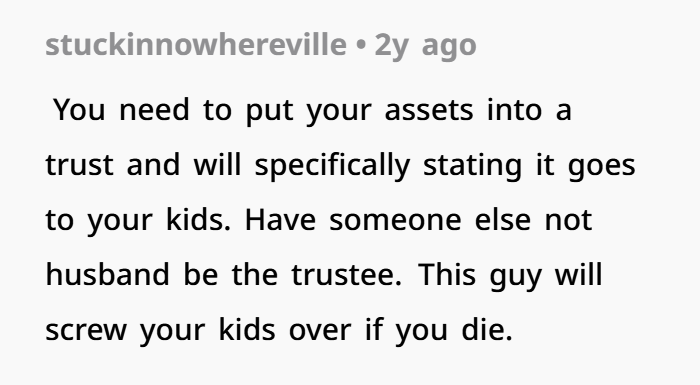
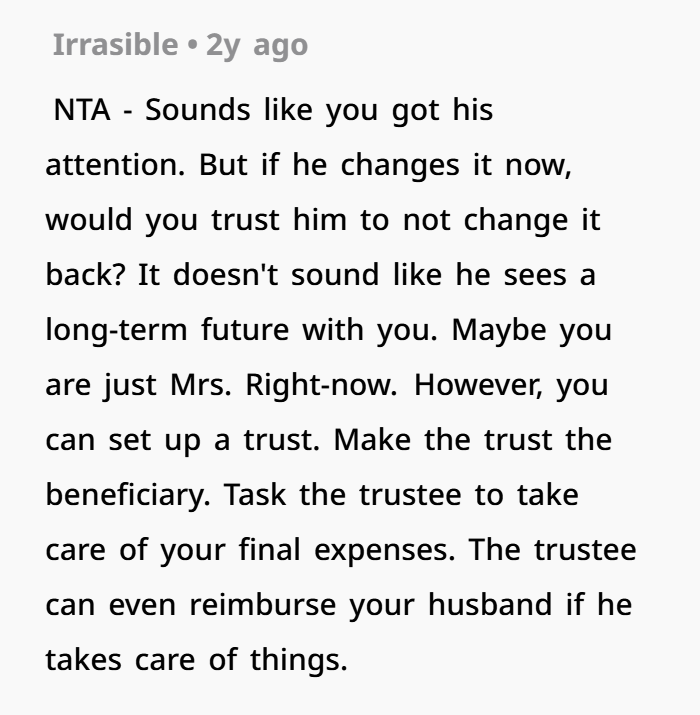
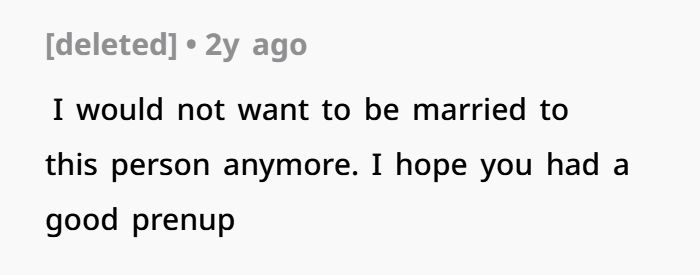
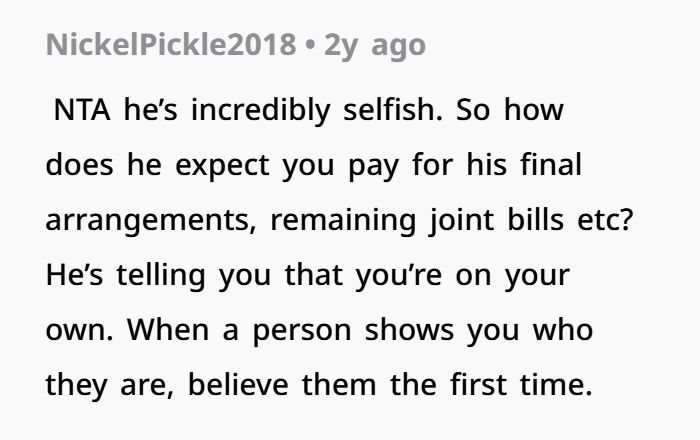

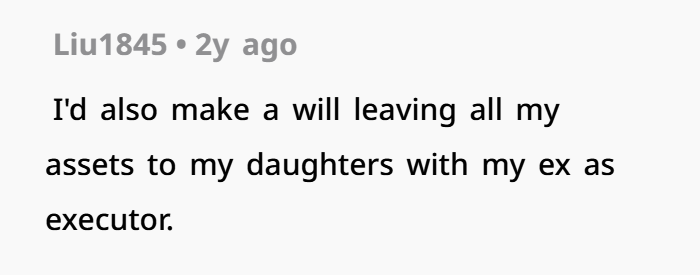
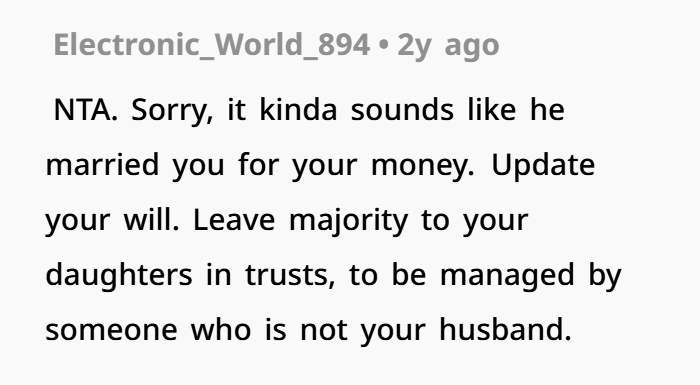
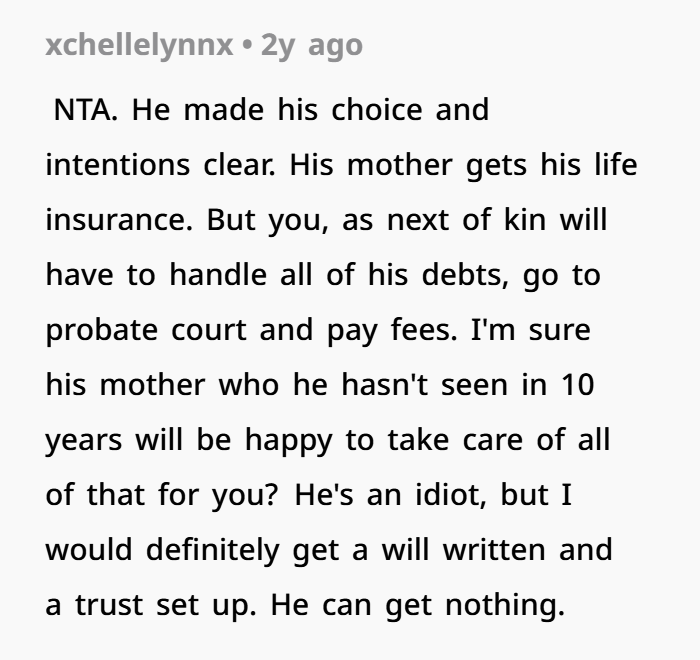

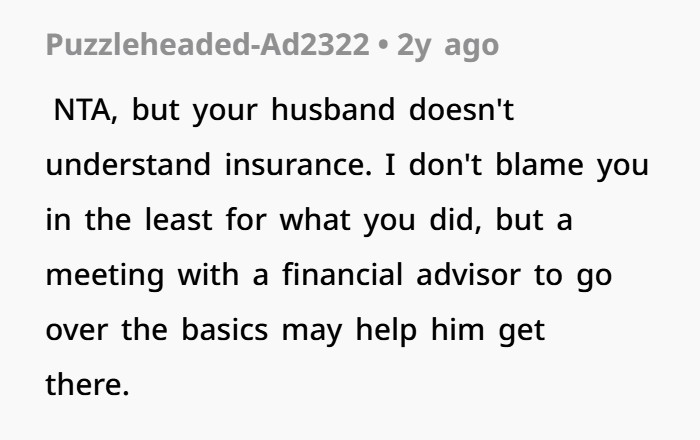
She didn’t rush into making her decision. She gave her husband time to think and explained why having financial support mattered so much to her. But even after several talks, he refused to name her as a beneficiary on his life insurance policy.
After that, she decided it was time to rethink her own plans. She canceled the policy she had bought for him and changed her other accounts so her children would receive the money instead.
For her, it wasn’t about getting back at her husband. She simply wanted to make sure her daughters would be taken care of if something happened to her.
Her husband was hurt by the changes, but she felt the situation was unfair from the start. He wanted to benefit from her insurance while refusing to offer her the same protection.
The disagreement shows why money talks matter in a marriage. Couples need to discuss life insurance, savings, retirement plans, and who will receive their assets in the future.
These talks can be even more important in second marriages, especially when children from past relationships are involved. Both partners may have family members they want to support, so clear plans can help avoid confusion and hurt feelings.
In the end, looking after your financial future isn’t selfish. It’s about knowing what matters to you, setting fair boundaries, and making sure the people you love have support when they need it most.
Make the ending more emotionally powerfulAdd a stronger closing question